Corporate greed is an easy, convenient answer to why things are so expensive … but I’ve tracked profits and revenue for the global “big oil” companies for a while now. Other than Armaco, and generally Petrobras, profits are under 10% of revenue. “Record profits” seem, generally, to come from record sales. We’re not going through record high profit percentages.
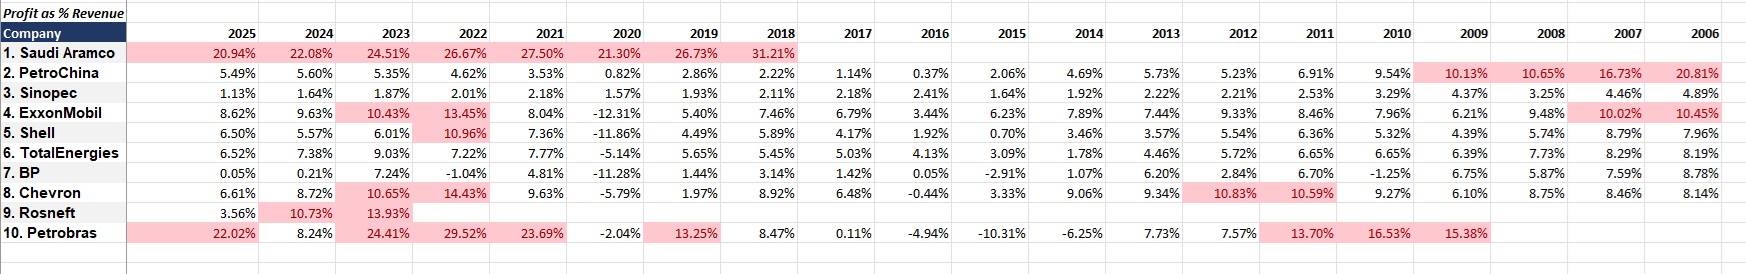
Now, a company that “only” profited five billion dollars on 380b isn’t doing badly and could probably have gotten by if they only made 2 million – but that makes for an interesting study. Say oil is $100 per barrel. 380 billion dollars is 3.8 billion barrels sold (yes, I know many of these companies have other lines of business. This is a thought experiment, not a regulated financial filing). If they earned three billion dollars less that year, the price per barrel would only drop $0.79. Under 1% change. Now, if Armaco had only profited 3.4 billion last year instead of 93.4b, that would be a $20/barrel drop.
Raw data:
| Company |
2025 |
2024 |
2023 |
2022 |
2021 |
2020 |
2019 |
2018 |
2017 |
2016 |
2015 |
2014 |
2013 |
2012 |
2011 |
2010 |
2009 |
2008 |
2007 |
2006 |
| Revenue ($B) |
Net profit ($B) |
Revenue ($B) |
Net profit ($B) |
Revenue ($B) |
Net profit ($B) |
Revenue ($B) |
Net profit ($B) |
Revenue ($B) |
Net profit ($B) |
Revenue ($B) |
Net profit ($B) |
Revenue ($B) |
Net profit ($B) |
Revenue ($B) |
Net profit ($B) |
Revenue ($B) |
Net profit ($B) |
Revenue ($B) |
Net profit ($B) |
Revenue ($B) |
Net profit ($B) |
Revenue ($B) |
Net profit ($B) |
Revenue ($B) |
Net profit ($B) |
Revenue ($B) |
Net profit ($B) |
Revenue ($B) |
Net profit ($B) |
Revenue ($B) |
Net profit ($B) |
Revenue ($B) |
Net profit ($B) |
Revenue ($B) |
Net profit ($B) |
Revenue ($B) |
Net profit ($B) |
Revenue ($B) |
Net profit ($B) |
| 1. Saudi Aramco |
446 |
93.4 |
481 |
106.2 |
495 |
121.3 |
604 |
161.1 |
400 |
110.0 |
230 |
49.0 |
330 |
88.2 |
356 |
111.1 |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
| 2. PetroChina |
399 |
21.9 |
409 |
22.9 |
426 |
22.8 |
481 |
22.2 |
405 |
14.3 |
280 |
2.3 |
364 |
10.4 |
356 |
7.9 |
298 |
3.4 |
244 |
0.9 |
277 |
5.7 |
371 |
17.4 |
365 |
20.9 |
348 |
18.2 |
298 |
20.6 |
216 |
20.6 |
149 |
15.1 |
155 |
16.5 |
110 |
18.4 |
86 |
17.9 |
| 3. Sinopec |
388 |
4.4 |
428 |
7.0 |
454 |
8.5 |
493 |
9.9 |
435 |
9.5 |
305 |
4.8 |
430 |
8.3 |
437 |
9.2 |
349 |
7.6 |
291 |
7.0 |
324 |
5.3 |
459 |
8.8 |
465 |
10.3 |
457 |
10.1 |
388 |
9.8 |
283 |
9.3 |
197 |
8.6 |
209 |
6.8 |
157 |
7.0 |
131 |
6.4 |
| 4. ExxonMobil |
334 |
28.8 |
350 |
33.7 |
345 |
36.0 |
414 |
55.7 |
286 |
23.0 |
182 |
-22.4 |
265 |
14.3 |
279 |
20.8 |
290 |
19.7 |
227 |
7.8 |
260 |
16.2 |
412 |
32.5 |
438 |
32.6 |
481 |
44.9 |
486 |
41.1 |
383 |
30.5 |
311 |
19.3 |
477 |
45.2 |
405 |
40.6 |
378 |
39.5 |
| 5. Shell |
274 |
17.8 |
289 |
16.1 |
323 |
19.4 |
386 |
42.3 |
273 |
20.1 |
183 |
-21.7 |
352 |
15.8 |
397 |
23.4 |
312 |
13.0 |
240 |
4.6 |
272 |
1.9 |
431 |
14.9 |
460 |
16.4 |
482 |
26.7 |
484 |
30.8 |
378 |
20.1 |
285 |
12.5 |
458 |
26.3 |
356 |
31.3 |
319 |
25.4 |
| 6. TotalEnergies |
201 |
13.1 |
214 |
15.8 |
237 |
21.4 |
284 |
20.5 |
206 |
16.0 |
140 |
-7.2 |
200 |
11.3 |
209 |
11.4 |
171 |
8.6 |
150 |
6.2 |
165 |
5.1 |
236 |
4.2 |
251 |
11.2 |
257 |
14.7 |
257 |
17.1 |
212 |
14.1 |
183 |
11.7 |
264 |
20.4 |
217 |
18.0 |
193 |
15.8 |
| 7. BP |
189 |
0.1 |
189 |
0.4 |
210 |
15.2 |
241 |
-2.5 |
158 |
7.6 |
180 |
-20.3 |
277 |
4.0 |
299 |
9.4 |
240 |
3.4 |
183 |
0.1 |
223 |
-6.5 |
354 |
3.8 |
379 |
23.5 |
387 |
11.0 |
376 |
25.2 |
297 |
-3.7 |
246 |
16.6 |
361 |
21.2 |
274 |
20.8 |
254 |
22.3 |
| 8. Chevron |
189 |
12.5 |
203 |
17.7 |
201 |
21.4 |
246 |
35.5 |
162 |
15.6 |
95 |
-5.5 |
147 |
2.9 |
166 |
14.8 |
142 |
9.2 |
114 |
-0.5 |
138 |
4.6 |
212 |
19.2 |
229 |
21.4 |
242 |
26.2 |
254 |
26.9 |
205 |
19.0 |
172 |
10.5 |
273 |
23.9 |
221 |
18.7 |
210 |
17.1 |
| 9. Rosneft |
101 |
3.6 |
109 |
11.7 |
107 |
14.9 |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
92 |
n/a |
63 |
n/a |
n/a |
n/a |
n/a |
11.1 |
n/a |
6.5 |
n/a |
n/a |
| 10. Petrobras |
89 |
19.6 |
91 |
7.5 |
102 |
24.9 |
124 |
36.6 |
84 |
19.9 |
54 |
-1.1 |
77 |
10.2 |
85 |
7.2 |
89 |
0.1 |
81 |
-4.0 |
97 |
-10.0 |
144 |
-9.0 |
141 |
10.9 |
144 |
10.9 |
146 |
20.0 |
121 |
20.0 |
91 |
14.0 |
n/a |
n/a |
n/a |
n/a |
n/a |
n/a |
Data as available. Publicly traded companies in US and Europe are far more apt to have published , audited, probably somewhat accurate data.