Corporate greed is an easy, convenient answer to why things are so expensive … but I’ve tracked profits and revenue for the global “big oil” companies for a while now. Other than Armaco, and generally Petrobras, profits are under 10% of revenue. “Record profits” seem, generally, to come from record sales. We’re not going through record high profit percentages.
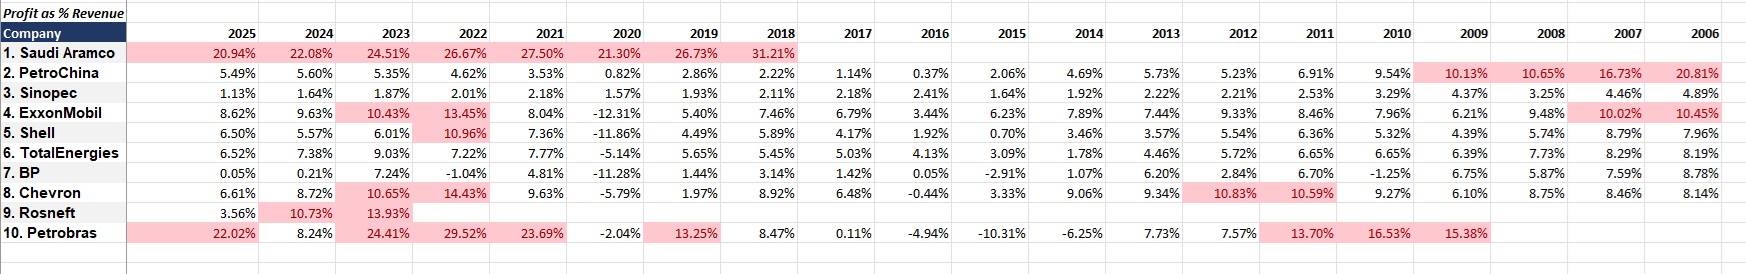
Now, a company that “only” profited five billion dollars on 380b isn’t doing badly and could probably have gotten by if they only made 2 million – but that makes for an interesting study. Say oil is $100 per barrel. 380 billion dollars is 3.8 billion barrels sold (yes, I know many of these companies have other lines of business. This is a thought experiment, not a regulated financial filing). If they earned three billion dollars less that year, the price per barrel would only drop $0.79. Under 1% change. Now, if Armaco had only profited 3.4 billion last year instead of 93.4b, that would be a $20/barrel drop.
Raw data:
| Company | 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | 2014 | 2013 | 2012 | 2011 | 2010 | 2009 | 2008 | 2007 | 2006 | ||||||||||||||||||||
| Revenue ($B) | Net profit ($B) | Revenue ($B) | Net profit ($B) | Revenue ($B) | Net profit ($B) | Revenue ($B) | Net profit ($B) | Revenue ($B) | Net profit ($B) | Revenue ($B) | Net profit ($B) | Revenue ($B) | Net profit ($B) | Revenue ($B) | Net profit ($B) | Revenue ($B) | Net profit ($B) | Revenue ($B) | Net profit ($B) | Revenue ($B) | Net profit ($B) | Revenue ($B) | Net profit ($B) | Revenue ($B) | Net profit ($B) | Revenue ($B) | Net profit ($B) | Revenue ($B) | Net profit ($B) | Revenue ($B) | Net profit ($B) | Revenue ($B) | Net profit ($B) | Revenue ($B) | Net profit ($B) | Revenue ($B) | Net profit ($B) | Revenue ($B) | Net profit ($B) | |
| 1. Saudi Aramco | 446 | 93.4 | 481 | 106.2 | 495 | 121.3 | 604 | 161.1 | 400 | 110.0 | 230 | 49.0 | 330 | 88.2 | 356 | 111.1 | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a |
| 2. PetroChina | 399 | 21.9 | 409 | 22.9 | 426 | 22.8 | 481 | 22.2 | 405 | 14.3 | 280 | 2.3 | 364 | 10.4 | 356 | 7.9 | 298 | 3.4 | 244 | 0.9 | 277 | 5.7 | 371 | 17.4 | 365 | 20.9 | 348 | 18.2 | 298 | 20.6 | 216 | 20.6 | 149 | 15.1 | 155 | 16.5 | 110 | 18.4 | 86 | 17.9 |
| 3. Sinopec | 388 | 4.4 | 428 | 7.0 | 454 | 8.5 | 493 | 9.9 | 435 | 9.5 | 305 | 4.8 | 430 | 8.3 | 437 | 9.2 | 349 | 7.6 | 291 | 7.0 | 324 | 5.3 | 459 | 8.8 | 465 | 10.3 | 457 | 10.1 | 388 | 9.8 | 283 | 9.3 | 197 | 8.6 | 209 | 6.8 | 157 | 7.0 | 131 | 6.4 |
| 4. ExxonMobil | 334 | 28.8 | 350 | 33.7 | 345 | 36.0 | 414 | 55.7 | 286 | 23.0 | 182 | -22.4 | 265 | 14.3 | 279 | 20.8 | 290 | 19.7 | 227 | 7.8 | 260 | 16.2 | 412 | 32.5 | 438 | 32.6 | 481 | 44.9 | 486 | 41.1 | 383 | 30.5 | 311 | 19.3 | 477 | 45.2 | 405 | 40.6 | 378 | 39.5 |
| 5. Shell | 274 | 17.8 | 289 | 16.1 | 323 | 19.4 | 386 | 42.3 | 273 | 20.1 | 183 | -21.7 | 352 | 15.8 | 397 | 23.4 | 312 | 13.0 | 240 | 4.6 | 272 | 1.9 | 431 | 14.9 | 460 | 16.4 | 482 | 26.7 | 484 | 30.8 | 378 | 20.1 | 285 | 12.5 | 458 | 26.3 | 356 | 31.3 | 319 | 25.4 |
| 6. TotalEnergies | 201 | 13.1 | 214 | 15.8 | 237 | 21.4 | 284 | 20.5 | 206 | 16.0 | 140 | -7.2 | 200 | 11.3 | 209 | 11.4 | 171 | 8.6 | 150 | 6.2 | 165 | 5.1 | 236 | 4.2 | 251 | 11.2 | 257 | 14.7 | 257 | 17.1 | 212 | 14.1 | 183 | 11.7 | 264 | 20.4 | 217 | 18.0 | 193 | 15.8 |
| 7. BP | 189 | 0.1 | 189 | 0.4 | 210 | 15.2 | 241 | -2.5 | 158 | 7.6 | 180 | -20.3 | 277 | 4.0 | 299 | 9.4 | 240 | 3.4 | 183 | 0.1 | 223 | -6.5 | 354 | 3.8 | 379 | 23.5 | 387 | 11.0 | 376 | 25.2 | 297 | -3.7 | 246 | 16.6 | 361 | 21.2 | 274 | 20.8 | 254 | 22.3 |
| 8. Chevron | 189 | 12.5 | 203 | 17.7 | 201 | 21.4 | 246 | 35.5 | 162 | 15.6 | 95 | -5.5 | 147 | 2.9 | 166 | 14.8 | 142 | 9.2 | 114 | -0.5 | 138 | 4.6 | 212 | 19.2 | 229 | 21.4 | 242 | 26.2 | 254 | 26.9 | 205 | 19.0 | 172 | 10.5 | 273 | 23.9 | 221 | 18.7 | 210 | 17.1 |
| 9. Rosneft | 101 | 3.6 | 109 | 11.7 | 107 | 14.9 | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a | 92 | n/a | 63 | n/a | n/a | n/a | n/a | 11.1 | n/a | 6.5 | n/a | n/a |
| 10. Petrobras | 89 | 19.6 | 91 | 7.5 | 102 | 24.9 | 124 | 36.6 | 84 | 19.9 | 54 | -1.1 | 77 | 10.2 | 85 | 7.2 | 89 | 0.1 | 81 | -4.0 | 97 | -10.0 | 144 | -9.0 | 141 | 10.9 | 144 | 10.9 | 146 | 20.0 | 121 | 20.0 | 91 | 14.0 | n/a | n/a | n/a | n/a | n/a | n/a |
Data as available. Publicly traded companies in US and Europe are far more apt to have published , audited, probably somewhat accurate data.